Understanding Difference Between Sum Insured and Sum Assured Concepts
Insurance terminology can sometimes be confusing, particularly when similar-sounding terms are used for different types of policies. Two important terms that policyholders commonly encounter are sum insured and sum assured.
Although both refer to the amount associated with an insurance policy, they are generally used in different insurance contexts and operate differently. In simple terms, sum insured is commonly associated with general and health insurance and represents the maximum amount payable for covered losses or expenses, while sum assured is primarily used in life insurance to describe the predetermined amount of life cover or benefit specified under the policy.
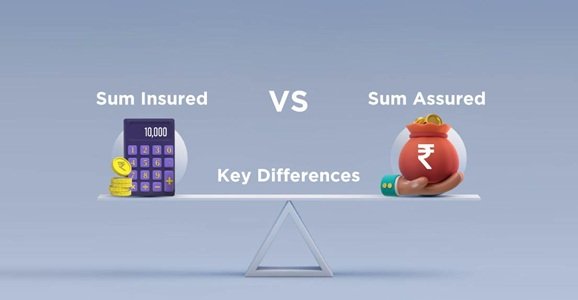
Understanding the distinction can help policyholders select appropriate coverage and interpret their policy documents correctly.
What Is Sum Insured?
Sum insured is the maximum amount an insurer agrees to pay for covered losses, expenses or claims under an insurance policy, subject to the policy’s terms and conditions.
It is commonly used in health insurance and many general insurance products.
For example, suppose a health insurance policy has a sum insured of ₹10 lakh. If the policyholder incurs eligible hospitalisation expenses of ₹6 lakh, the insurer may pay the covered amount subject to applicable conditions, limits, exclusions, deductibles and co-payments.
If the eligible expenses are ₹12 lakh, the policy does not automatically pay the entire ₹12 lakh merely because the treatment was medically necessary. The applicable sum insured and other policy conditions determine the insurer’s liability.
The exact meaning can vary according to the policy wording. For example, IRDAI-hosted insurance policy documentation defines sum insured as the amount specified in the policy schedule that forms the limit of the insurer’s liability.
What Is Sum Assured?
Sum assured is generally associated with life insurance and represents the amount of life insurance cover or benefit specified in the policy.
For example, if a person purchases a term life insurance policy with a sum assured of ₹1 crore, the policy provides the specified life cover according to its terms.
If the insured event occurs while the policy is in force and the claim satisfies the policy conditions, the applicable death benefit may be based on the sum assured, subject to the specific policy structure.
IRDAI-hosted life insurance policy documents define sum assured as an amount of life insurance cover specified under the policy.
However, the actual amount payable in a life insurance policy can depend on the product’s benefit structure, riders, bonuses, deductions and other applicable provisions. Therefore, the sum assured should not automatically be assumed to be the final amount payable in every type of life policy.
The Basic Difference
The easiest way to remember the distinction is:
Sum insured → commonly used for health/general insurance and represents the coverage limit for covered losses or expenses.
Sum assured → commonly used in life insurance and represents the specified life insurance benefit or cover.
The terms should always be interpreted according to the individual policy because insurers may use terminology differently for particular products.
Sum Insured in Health Insurance
Health insurance is one of the most common situations where the term sum insured is used.
Suppose a policyholder has a ₹5 lakh health insurance policy.
During a policy year, the person incurs:
- Hospitalisation expenses: ₹2 lakh
- Eligible diagnostic expenses: ₹50,000
- Other covered expenses: ₹1 lakh
If all these expenses are covered under the policy, the insurer may pay eligible expenses up to the applicable policy limits.
But the ₹5 lakh sum insured does not necessarily mean that every medical bill will be reimbursed.
Health insurance policies can contain:
- Room-rent limits
- Disease-specific sub-limits
- Co-payment
- Deductibles
- Waiting periods
- Exclusions
- Network hospital conditions
- Treatment-specific restrictions
Therefore, the sum insured is best understood as the overall coverage limit rather than an unconditional reimbursement promise.
Example of Sum Insured
Consider a health insurance policy with a sum insured of ₹10 lakh.
Suppose the policyholder has an eligible hospital bill of ₹4 lakh. If the entire amount is covered and there are no applicable deductions, the insurer may pay ₹4 lakh.
The remaining ₹6 lakh does not become a cash payout to the policyholder.
This is an important difference between insurance protection and an investment account. The sum insured represents the insurer’s potential liability for covered claims, not money automatically received by the policyholder.
Sum Assured in Life Insurance
In life insurance, the sum assured is generally linked to the benefit payable upon the occurrence of the insured event, particularly death in a pure term insurance policy.
For example, suppose a policyholder purchases:
Life cover: ₹1 crore
If the policyholder dies during the policy term and the claim is admissible, the applicable death benefit may be ₹1 crore under a simple level-cover term insurance structure.
However, other life insurance products can have more complicated benefit structures.
For example, a participating policy may provide a basic sum assured plus applicable bonuses. A policy with riders may provide additional benefits for specified events.
Therefore, the policy schedule and benefit illustration should always be checked to understand exactly what is payable.
Sum Insured vs Sum Assured: Key Differences
| Feature | Sum Insured | Sum Assured |
| Commonly associated with | Health/general insurance | Life insurance |
| Basic meaning | Coverage limit for insured losses/expenses | Specified life insurance cover/benefit |
| Common example | ₹10 lakh health cover | ₹1 crore term life cover |
| Payment basis | Actual eligible loss/expense, subject to policy terms | Benefit specified under the life policy |
| Claim frequency | Can involve multiple claims depending on policy | Usually linked to specified insured events |
| Deductibles/sub-limits | Common | Product-dependent |
| Main purpose | Protect against financial loss or medical expenses | Provide financial protection linked to life/insured events |
Does a Higher Amount Always Mean Better Coverage?
Not necessarily.
A policy with a higher sum insured or sum assured may provide more financial protection, but the overall usefulness of the policy depends on its terms.
For health insurance, a ₹20 lakh sum insured with significant exclusions or restrictive sub-limits may not necessarily provide the same practical protection as another policy with broader coverage.
Similarly, in life insurance, the appropriate sum assured depends on factors such as income, dependants, liabilities, financial goals and the period for which protection is required.
The policyholder should therefore look beyond the headline amount.
How Sum Insured Can Change
Health insurance policies can provide mechanisms such as cumulative bonuses, restoration benefits or increases in coverage, depending on the product.
For example, a policy may provide a cumulative bonus for claim-free years, increasing the available coverage subject to the policy’s rules.
Some policies may also restore the sum insured after a claim under specified circumstances.
These features do not necessarily mean that the base sum insured permanently changes. The policy wording should explain how the benefit operates.
How Sum Assured Can Change
Life insurance coverage can also vary depending on the product.
A basic term plan may maintain a level sum assured throughout the policy term.
Other products may provide increasing or decreasing life cover.
For example, a reducing life insurance policy may have a schedule showing how the sum assured decreases over time. IRDAI-hosted policy documentation includes examples where a schedule specifies the sum assured applicable in each policy year.
This is why policyholders should check whether their life cover is level, increasing or decreasing.
Why Understanding These Terms Matters
Confusing sum insured with sum assured can lead to incorrect expectations about claim payments.
For health insurance, policyholders should understand that the sum insured is not necessarily the amount they receive as cash. It is generally the maximum coverage available for eligible claims, subject to the policy.
For life insurance, the sum assured represents the specified life cover, but the final benefit can depend on the policy’s structure and applicable provisions.
Understanding these concepts can also make it easier to compare insurance products and identify differences in premiums, coverage limits and benefits.
What Should Policyholders Check?
Before purchasing an insurance policy, review:
- Coverage amount
- Policy term
- Exclusions
- Waiting periods
- Deductibles
- Co-payment provisions
- Sub-limits
- Claim conditions
- Riders and additional benefits
- Renewal or continuation provisions
Do not rely solely on the sum insured or sum assured displayed in advertisements. The policy wording and schedule contain the contractual details that determine coverage.
Conclusion
The concepts of sum insured and sum assured are fundamental to understanding insurance.
Sum insured is commonly used in health and general insurance to describe the coverage limit available for eligible losses or expenses. Sum assured is primarily associated with life insurance and represents the specified amount of life insurance cover under the policy.
For example, a health policy may have a ₹10 lakh sum insured, while a term life insurance policy may provide a ₹1 crore sum assured.
However, the headline amount alone does not determine the complete protection offered by an insurance policy. Exclusions, deductibles, sub-limits, waiting periods, claim conditions and product-specific benefits can all affect the amount ultimately payable.
Therefore, when comparing insurance policies, it is important to understand not only how much the policy covers but also what is covered, under what circumstances and subject to which conditions.